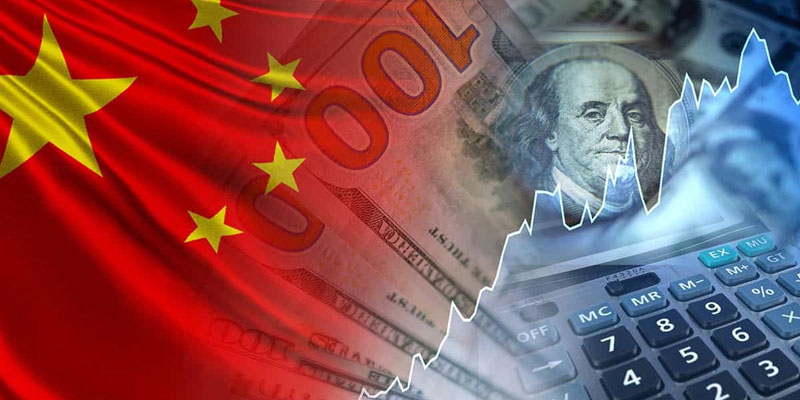
A significant, yet subtle, reorientation is underway in the global financial landscape as Asian nations, spearheaded by the BRICS economic bloc, steadily reduce their holdings of U.S. assets. This calculated divestment signals a potential re-architecture of the international monetary system, placing an estimated $7.5 trillion in U.S. holdings at risk amidst escalating geopolitical tensions and burgeoning doubts over American fiscal stability.
China, a key member of the BRICS coalition, has notably offloaded $150 billion in U.S. Treasury bonds in 2024 alone, reflecting a strategic move to diminish its reliance on the U.S. dollar. This trend is not isolated; other BRICS nations and several broader Asian economies are also actively divesting from U.S. financial assets. This collective acceleration towards diversification favors tangible assets like gold and other perceived safer stores of value.
For decades, Asia's economic framework largely relied on exporting goods to the United States and subsequently reinvesting the earned capital into U.S. debt securities. However, mounting concerns over America's rapidly expanding national debt, which has now exceeded $36 trillion, are compelling a profound reassessment of this long-standing model. Analysts caution that a broader movement of the remaining $7.5 trillion in Asian assets currently linked to U.S. markets could trigger severe repercussions for the American economy.
This evolving financial dynamic transcends mere economic recalibration; it signifies a deeper questioning of the post-World War II financial architecture. As articulated by Virginie Maisonneuve of Allianz Global Investors, "We are witnessing a change in the world order, and it is unlikely we will return to previous norms."
The shift is significantly propelled by China’s increasing technological and economic influence, with emerging markets progressively asserting their financial sovereignty. This pivot away from the dollar, strategically bolstered by increased gold reserves, reflects a palpable unease regarding the long-term stability and resilience of the U.S. dollar as the world's primary reserve currency.
Should this trend intensify, the United States could face substantial consequences, including a diminished global financial influence, elevated borrowing costs, and a weakening dollar. Concurrently, emerging powers, particularly within the BRICS framework, are strategically positioning themselves to capitalize on this transition by actively promoting alternative reserve currencies and developing new financial systems.
While the era of the U.S. dollar as the dominant global currency is not yet concluded, the foundational elements for a new monetary chapter are being quietly laid. The emerging landscape suggests that the long-anticipated epilogue of U.S. dollar dominance may well be underway.